
What happens to your pension when you change jobs
By Rive News / Research desk | Rive News / Published October 29, 2026 at 9:00 AM PKT
Key takeaways
- Changing jobs does not lose your pension: the old pot stays in your name and stays invested.
- You can leave the pot where it is, move it to a new employer's scheme, or move it to a personal pension.
- Check charges and valuable guarantees before transferring, since some benefits cannot be recovered once given up.
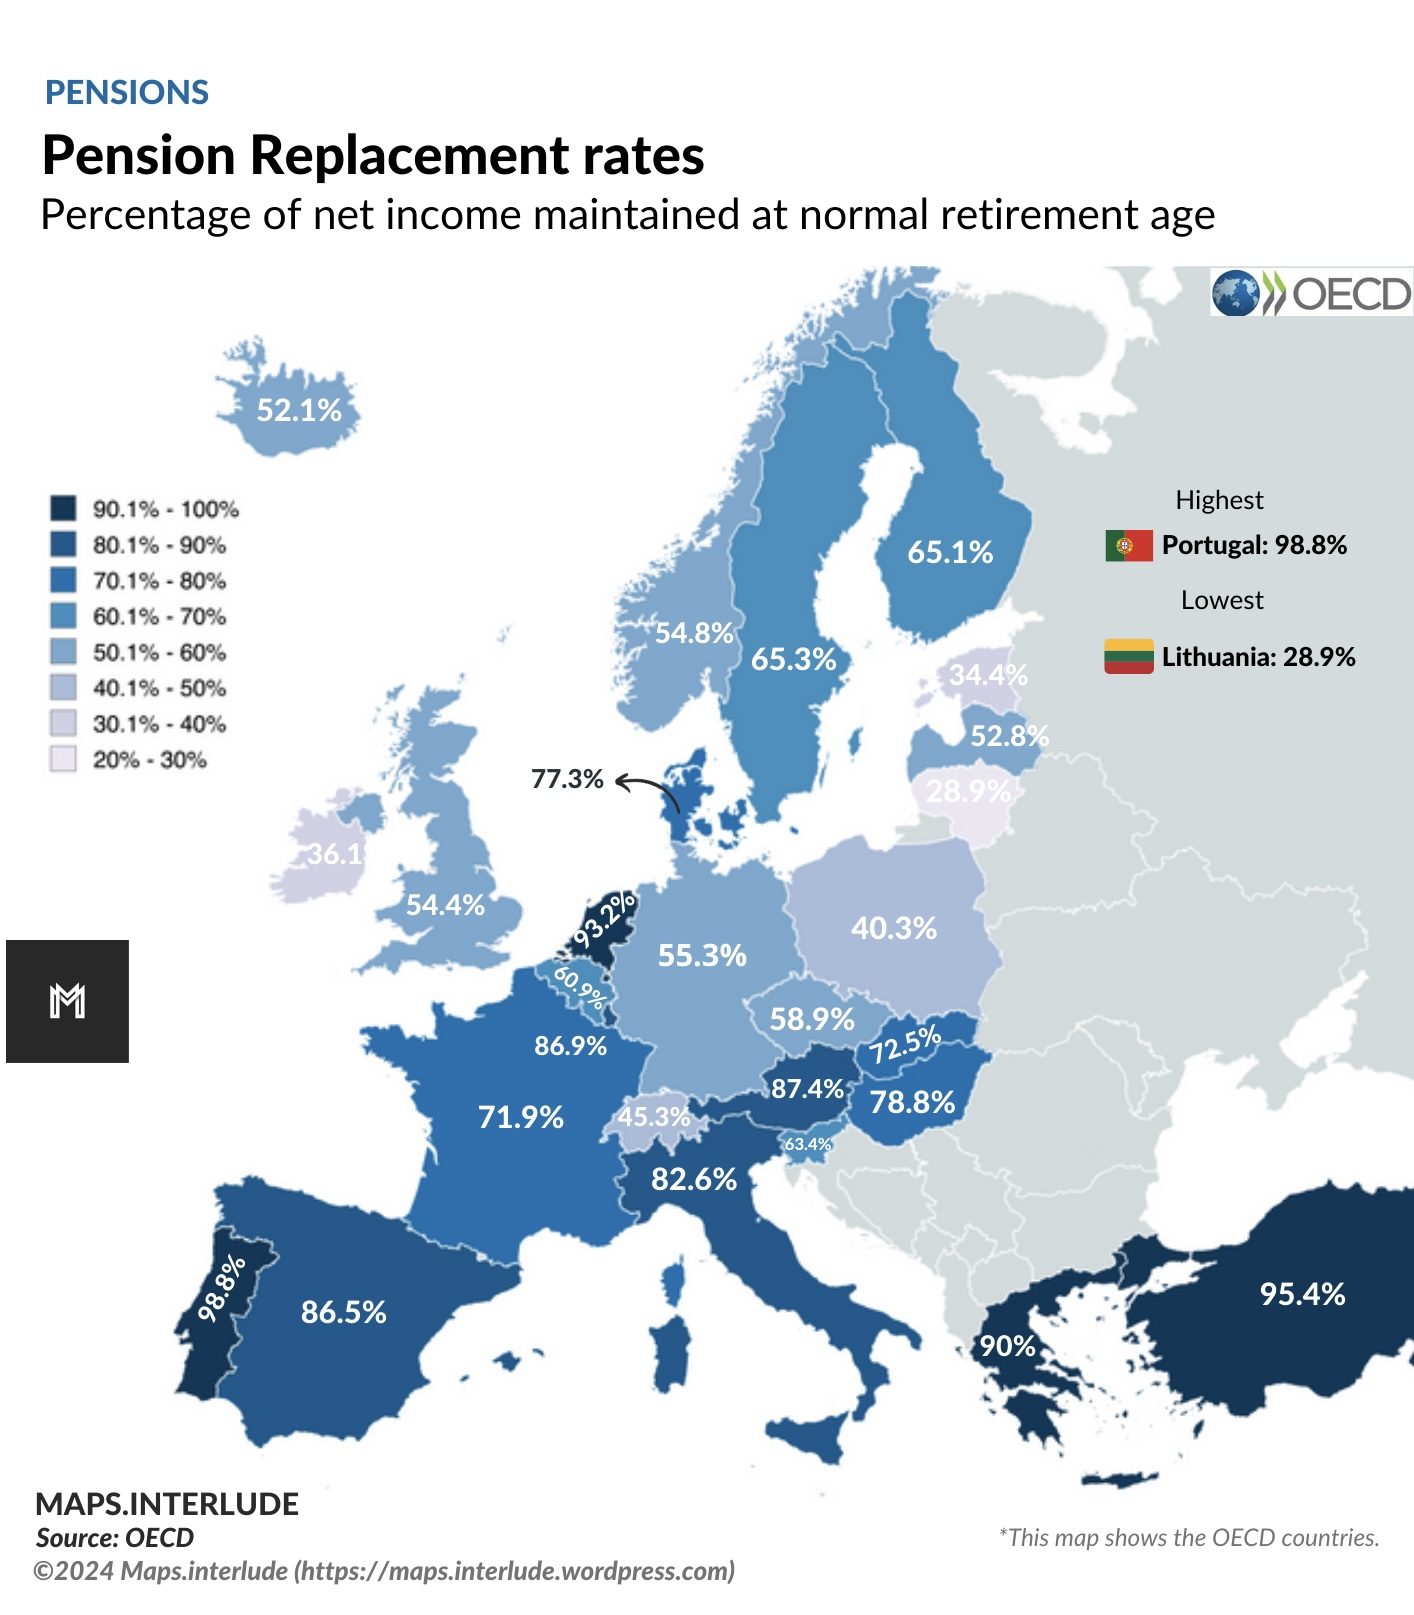
[A chart comparing pension replacement rates.] Photograph: Wikimedia Commons contributor
Image Credits: Wikimedia Commons
Changing jobs does not wipe out the pension built up with a previous employer. The money stays in the saver's name, usually invested, until it is taken in retirement or moved deliberately. What changes is who pays in next, and where the next pot starts.
This article explains what happens to a pension when you change jobs, including the three main options for an old pot, the checks to make before transferring, and how to trace a pot that has been forgotten. It focuses on the United Kingdom system, where most of the cited guidance applies.
This is general educational information, not financial advice.
The short answer: the pot stays put
Royal London states the position plainly: if you change jobs, you do not lose your pension. It stays in your name and usually remains invested until you start taking it. If you do nothing, it will simply stay invested where it is, with its growth depending on investment performance and charges.
That rule holds because a workplace pension pot belongs to the saver, not the employer. Leaving a job ends the employer's contributions to that scheme, but it does not cancel the savings already made. The saver becomes a deferred member of the old scheme, meaning no new money goes in from that employer, while the existing pot remains invested.
A new job starts a separate process. The new employer assesses the saver under automatic enrolment rules and enrols them in its own scheme if the legal tests are met. Over a career, that pattern can leave a person with several small pots, one per employer, which is why keeping a record matters.
Option one: leave the old pot where it is
Leaving a pot untouched is a reasonable choice when the fund is good and charges are low. Interactive Investor notes that a saver can have as many pensions as they like, so freezing the old pension and joining another scheme with a new employer is entirely normal.
Two housekeeping tasks go with this option. The provider needs a current address, or statements will go to an old home and the pot may drift out of sight. The saver should also keep a note of the provider's name and any policy number, since those details are needed later to trace the pot.
Charges deserve a look even when nothing is moved. An old scheme may charge more than a new one, or invest in a fund that no longer suits the saver. Leaving a pot alone is not the same as ignoring it.
Option two: move it to the new employer's scheme
Transferring the old pot into the new employer's workplace scheme brings the savings together in one place. That can make the total easier to track and can reduce the number of statements to follow. Interactive Investor notes that a pension can follow a saver throughout a career and be transferred as many times as they move jobs, although there may be costs for moving the money.
The new scheme must accept transfers, and not every scheme does, so the first step is to ask. The transfer is usually handled between providers, and the money should move as pension savings, not as cash to the saver, so its tax treatment is preserved.
One warning applies before any transfer. Interactive Investor quotes independent financial adviser Andrew McCombe, who says transferring might not always be in a saver's best interest, particularly for a defined benefit scheme with a guaranteed final salary income. Giving up a guaranteed income for a pot of invested money is a decision that cannot easily be undone.
Option three: move it to a personal pension
The third option is a personal pension, such as a self-invested personal pension, which is not tied to any employer. This route suits savers who want one pot they control across several jobs, or who are moving to self-employment and will have no workplace scheme to transfer into.
Royal London notes that a saver who becomes self-employed will usually set up their own pension to pay into, while the old pension remains where it is unless a transfer is chosen. The same logic applies to a saver between jobs: the old pot waits, and new saving can go into a personal pension in the meantime.
A personal pension brings its own charges and investment choices, so the comparison is not just about convenience. Compare the annual charge, the range of funds, and any exit charge on the old scheme before deciding consolidation is worth it.
The checks to make before transferring
Three checks matter more than any other. The first is charges: compare the old scheme's annual charge with the new scheme's charge on a like-for-like basis. A difference of even a fraction of a percent compounds over decades.
The second is guarantees. McCombe warns that savers should not give up valuable features of an old scheme, such as a guaranteed annuity rate, which would allow them to buy a higher level of income in retirement. Other guarantees can include a protected retirement age or a guaranteed minimum income, and these are often worth more than the headline pot value.
The third is exit penalties. Some older schemes charge for leaving, and some restrict transfers for a period. Bestinvest, in its guide to leaving a company pension, advises savers to consider whether they will lose valuable benefits and whether they will incur penalties on the existing pension if they transfer.
For defined benefit pensions worth more than £30,000, regulated advice is required before a transfer in the UK. That threshold, set out in pension transfer regulations, is a useful reminder that larger and more complex pots deserve professional advice rather than a form filled in alone.
What happens to employer contributions
When employment ends, the employer's contributions to that scheme stop. The employee's own contributions stop too, unless the scheme allows continued personal payments after leaving, which some do. The pot itself keeps its value, minus charges, and keeps being invested.
Automatic enrolment at the new employer works independently. Under the standard qualifying-earnings basis, the legal employer minimum is 3% of qualifying earnings, with at least 8% going in overall including the worker's share and tax relief. Those figures, reported in a 2026 workplace pension guide, are minimums, and many employers pay more.
Opting out of the new scheme is possible, but it forfeits the employer contribution, which is effectively part of pay. A saver who opts out should be sure the decision is deliberate, not a missed form during a busy first week.
How to trace a forgotten pot
Forgotten pots are common, especially after short jobs or house moves. The UK government runs a free Pension Tracing Service, which Boring Money describes as the starting point for a lost pot.
It can be used online at gov. uk/find-pension-contact-details or by phone on 0800 731 0193.
The service has a clear limit that savers should understand. It returns the contact details of the scheme's administrator, not the balance or value of the pot. The saver must then contact the administrator directly, with a National Insurance number, employment dates and old addresses, to find out whether a pot exists and what it is worth.
Gathering old payslips or P60s helps, because they usually name the provider or scheme. Old colleagues can also help when an employer has changed its name or been taken over, since the scheme administrator may now be a different company from the employer.
Watch out for pension scams at job changes
A job change is a moment when pension scams become more likely. Royal London lists the warning signs: unexpected contact about a pension, an offer of a free pension review, pressure to transfer quickly, promises of unusually high returns, and offers of help to access a pension early.
Early access is a particular red flag. The normal minimum pension age in the UK is 55, rising to 57 on 6 April 2028, and access before that age is only possible in very limited circumstances, such as serious ill health. Anyone offering to unlock a pension early is almost certainly running a scam, according to workplace pension guidance.
Any adviser or firm involved in a transfer should be authorised by the Financial Conduct Authority. The FCA register can be checked before signing anything, and a genuine provider will not object to that check.
[A 19th-century painting showing a pension payment day.] Photograph: Vladimir Makovsky, public domain via Wikimedia Commons
Image Credits: Wikimedia Commons
Frequently asked questions
Do I lose my pension if I leave my job?
No. The pot stays in your name and usually remains invested. Only future contributions from that employer stop, and the saver can leave the pot, transfer it to a new scheme, or move it to a personal pension.
Can I cash in my pension when I change jobs?
Not normally. Pension savings cannot usually be taken before the normal minimum pension age, which is 55 and rises to 57 on 6 April 2028. Changing jobs does not create a right to withdraw the money early.
Should I combine all my old pensions into one?
It depends on charges, investment options and guarantees. Consolidation makes tracking easier, but transferring away from a scheme with a guaranteed annuity rate or other valuable feature can cost more than it saves.
How do I find a pension from an old employer?
Use the government's free Pension Tracing Service online or by phone, with the employer's name and employment dates. It gives the administrator's contact details, and the administrator can then confirm the pot and its value.
What happens to my State Pension when I change jobs?
Nothing changes. The State Pension is separate from workplace pensions and is based on National Insurance record, not on any single employer. Changing jobs does not reset it.
The bottom line
A job change leaves the old pension pot intact and starts a new one. The decision that matters is what to do with the old pot, and the safest approach is to compare charges, check for guarantees, and trace any pot that has gone quiet before moving anything.
Keeping a simple record, one line per employer with the provider name and a policy number, prevents most pension headaches later. It also helps a saver judge whether total saving is on track. Readers planning the next step may also want to read what a pension is and how retirement saving works and what happens to a 401k when you quit a job.
Tags: pensions, changing jobs, retirement saving
Rive News is a research desk that writes plain-English explainers from public sources, with claims checked against the documents cited.
Related
- What is a pension and how retirement saving works
- What happens to your 401k when you quit a job
- How a credit card grace period actually works
- Why savings account rates differ so much between banks
Subscribe for a weekly explainer on the money topics readers ask about most.
Rive News publishes general educational explainers. Figures and policies cited here come from the public sources listed above and can change; check the scheme's current terms before acting.
Related stories

How your APR is divided by 365 to get daily interest
Lenders divide your APR by 365 for a daily rate, then apply it to your average daily balance. This guide walks through every step

What is the difference between APR and effective annual rate?
APR ignores compounding inside the year; the effective annual rate includes it. A 12.99% APR card really costs 13.80% a year. Worked

APY vs interest rate: what compounding does to your money
APY includes compounding; the interest rate does not. A 5% rate compounded monthly is really 5.12% APY. Here is how the math works and what