How to Start Investing With Very Little Money
Key takeaways
- You can start with as little as $1 through fractional shares at brokerages with no account minimum.
- Build a small cash cushion and clear high-interest card debt before you invest.
- One low-cost broad index fund, bought on autopilot, beats a scattered handful of stock picks.
Starting to invest used to mean saving up a large lump sum first. That barrier is gone. Fractional shares now let you buy a slice of a fund for a single dollar, and several large brokerages charge no account minimum and no commission on most online stock and ETF trades.
The hard part is no longer the amount. It is opening the account, making the first purchase, and leaving the money alone long enough for compounding to work. This article explains how to start investing with very little money, in the order that protects a small balance: cushion first, debt second, account third, fund fourth.
This article is for general information, not financial advice.
First, build a small cushion
Before you invest, keep a small emergency fund and clear high-interest card debt. Otherwise, a surprise bill could force you to sell at a bad time, or interest charges could outrun any market gain. Bee Bulletin gives this step first for exactly that reason.
The cushion does not need to be large. Even $500 to $1,000 in savings keeps a flat tyre or a broken appliance from tapping your investments. Beginner Bull suggests aiming for about eight weeks of essential expenses, such as rent, food, and utilities, tucked away in a high-yield savings account before investing more seriously.
Many households run thin. According to the Federal Reserve's Survey of Household Economics and Decisionmaking, 63 percent of US adults said in the 2025 survey that they could cover a $400 emergency expense completely with cash or its equivalent. If you are in the other third, the cushion comes before the brokerage account.
Money you need within the next few years generally belongs in savings, not stocks. The FDIC insures deposits to at least $250,000 per depositor at each insured bank, according to Bee Bulletin. Investments carry no such guarantee.
Second, kill expensive debt
Pay off high-interest debt before investing. Beginner Bull states the rule plainly: if you carry credit card debt at 20 percent interest, clear that first, because no stock market return can consistently beat the guaranteed 20 percent win from clearing that debt.
Lower-interest debt is different. A mortgage or a federal student loan can reasonably be paid on schedule while you invest at the same time. The dividing line is the interest rate compared with what markets might return, and credit card rates sit far above it.
If you are deciding between saving and investing with a small monthly surplus, the same order applies: cushion, expensive debt, then investing. Each step protects the next one.
Third, pick the account type
Next, decide whether the money is for retirement or for goals sooner than that. If it is for retirement and you have earned income, a Roth IRA is usually the best first account for a beginner, according to Bee Bulletin. Otherwise, a regular taxable brokerage account gives you full flexibility.
The 2026 IRA limit is $7,500, according to the IRS as cited by Bee Bulletin. Roth IRA eligibility phases out between $153,000 and $168,000 of income for single filers. Your IRA contributions cannot exceed your taxable compensation for the year.
If your employer offers a 401(k) match, contribute at least enough to get the full match before funding an IRA. A match is extra money you would otherwise leave on the table. That step alone beats any fund choice you will make later.
A taxable brokerage account has no contribution limit, and you can withdraw money at any time. You pay taxes on dividends and gains. For goals before retirement, such as a house deposit in ten years, that flexibility is worth the tax drag.
Fourth, choose a low-cost broker
Open an account with a broker that has no account minimum, $0 online stock and ETF commissions, and fractional shares. Fidelity, Charles Schwab, and Robinhood all let you buy fractional shares from $1, with no account minimum at Fidelity, according to Bee Bulletin.
Fractional shares are the key change for small investors. The SEC's Investor.gov bulletin on fractional share investing explains that if a stock trades at $1,000 and you have $100, you can buy 0.1 shares.
DebtZeroo gives the same example in ETF form: if one share of an S&P 500 ETF costs $500 and you invest $50, you own 0.10 of a share. You still participate proportionally in gains, losses, and dividends.
Before you deposit, you can confirm the firm and its representatives on FINRA's free BrokerCheck tool, as Bee Bulletin recommends. Transfers from your bank usually take one to a few business days to settle, so the cash may show as pending at first.
Watch out for flat monthly fees on tiny balances. Bee Bulletin notes that Betterment charges $5 a month on balances under $24,000 unless you set up recurring deposits of $200 or more a month. On a $100 balance, that is $60 a year, or 60 percent of your money.
Fidelity Go charges no advisory fee under $25,000. A flat fee can swallow a small account before the market gets a chance.
Fifth, buy one broad index fund
For most beginners, the best thing to buy with a small amount is a single low-cost index fund that tracks the whole US market or the S&P 500. An index fund is a mutual fund or ETF that simply copies a market index instead of paying managers to pick stocks. One fund gives you instant diversification across hundreds or thousands of companies.
The cost advantage is large. Vanguard's S&P 500 ETF (VOO) charges a 0.03 percent annual expense ratio, according to Vanguard data cited by Bee Bulletin.
That works out to about 3 cents a year on a $100 balance. Vanguard's Total Stock Market ETF (VTI) charges the same 0.03 percent and holds about 3,500 US stocks.
Enter a dollar-based order rather than a share order. Because you are buying in dollars, the full amount gets invested, even if one share costs far more than your deposit. Beginner Bull puts it simply: with $1 to $50, open a brokerage account with no minimum and buy a fractional share of a broad index fund.
Keep individual stocks as a small side position, if you want them at all. Bee Bulletin suggests putting $80 into a broad index fund and $20 into one or two companies you understand.
That way, you learn how single stocks behave without betting everything on them. One bad company cannot sink a fund that holds hundreds.
Note one limit of fractional shares: Investor.gov notes that you generally cannot transfer fractional shares to another brokerage, and you may not get voting rights. Those limits rarely matter for a beginner, but they are worth knowing before you build a large position.
Sixth, automate and leave it alone
Set up a recurring transfer and automatic investment, even if it is just $25 a month. Investing a fixed amount on a schedule, often called dollar-cost averaging, means you buy more shares when prices are low and fewer when they are high. Above all, it removes the temptation to guess where the market is going.
Turn on dividend reinvestment. The small dividends your fund pays go straight back into more shares instead of sitting idle as cash. Over decades, reinvested dividends make up a large share of total returns.
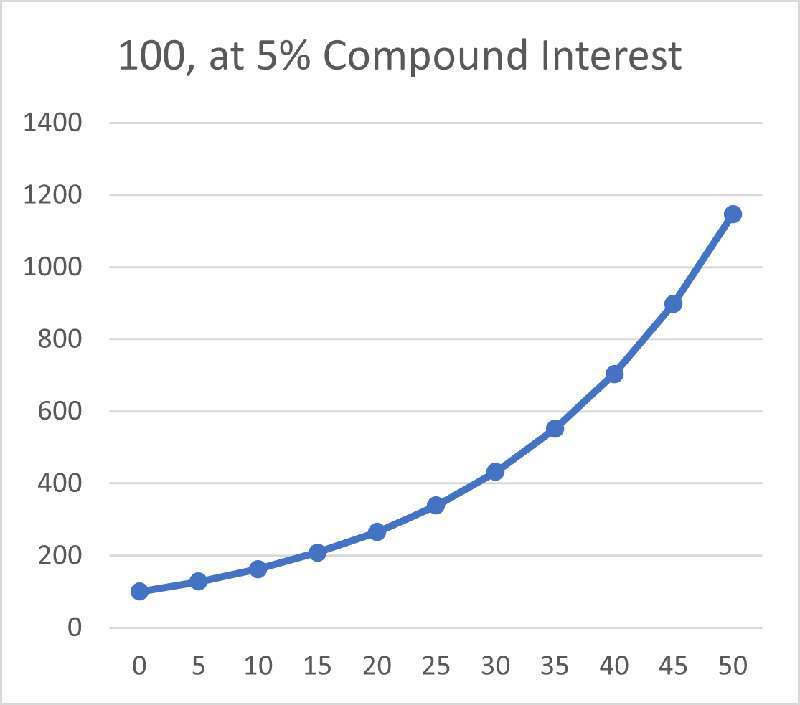
The math rewards patience more than a large first deposit. Bee Bulletin shows that $100 a month for 30 years grows to about $69,405 at a hypothetical 4 percent a year, about $100,452 at 6 percent, and about $149,036 at 8 percent, with monthly compounding. The table is a hypothetical illustration, not a forecast, and it ignores fees, taxes, and inflation.
By comparison, a one-time $100 deposit left alone for 30 years would grow to about $324 at 4 percent or about $1,006 at 8 percent. Regular contributions matter far more than the size of the first deposit.
Check your balance rarely. Daily price swings are noise, and investors who check constantly tend to make emotional decisions.
A quarterly glance is enough for a long-term account. If a market drop makes you want to sell, remember that the drop is when your automatic monthly buy picks up more shares for the same money.
Money saved on groceries can fund the monthly habit. If your food bill still has room to fall, the steps in our guide on saving money on groceries without eating worse can free up the first $25 or $50 a month.
Frequently asked questions
How much money do I need to start investing?
You can start with as little as $1 at most major brokerages thanks to fractional shares and $0 minimum funds. The practical floor is whatever you can afford to set aside each month without touching it. Starting is more important than the amount.
Can I start investing with $10 a month?
Yes. Ten dollars a month is a fine starting point.
What matters most is that you start and stay consistent. Raise the amount when your income rises, and automate the increase so it happens without a decision.
Should I pay off debt or invest first?
Pay off high-interest debt, anything above roughly 6 to 8 percent APR such as most credit cards, before investing. That interest is a guaranteed cost you eliminate. Lower-interest debt can reasonably be paid on schedule while you invest at the same time.
Are index funds safe?
Index funds are diversified, which means no single company's failure can wipe you out, but they still rise and fall with the market. In 2008 to 2009, the S&P 500 dropped about 50 percent. Index funds suit long-term money you will not need for five years or more, not money you need next year.
What about crypto or quick returns?
Bitcoin and other crypto assets can be bought with $100 on many apps, but they are highly volatile and not a substitute for a diversified fund. Treat any such position as a small slice of money you can afford to lose entirely.
Be sceptical of any pitch for a quick return. The SEC's Investor.gov fraud guide warns that promises of guaranteed returns are a red flag.
The bottom line
Starting to invest with very little money follows a simple order. Build a small cushion, clear expensive debt, pick the right account, open a no-minimum brokerage, buy one low-cost broad index fund with fractional shares, and automate a monthly deposit.
The amount you start with matters far less than the habit you build. Open the account, make the first purchase, and let time do the heavy lifting.
This article is for general information, not financial advice.
Tags: investing, index funds, personal finance, beginners, saving money
Latest in Finance
- How to Save Money on Groceries Without Eating Worse
- How to Build an Emergency Fund on a Low Income
- How to Budget When Your Income Changes Every Month
- How to Ask for a Raise Without Sounding Greedy
Subscribe for one practical money habit each week, written in plain English.
Related stories
How your APR is divided by 365 to get daily interest
Lenders divide your APR by 365 for a daily rate, then apply it to your average daily balance. This guide walks through every step
What is the difference between APR and effective annual rate?
APR ignores compounding inside the year; the effective annual rate includes it. A 12.99% APR card really costs 13.80% a year. Worked
APY vs interest rate: what compounding does to your money
APY includes compounding; the interest rate does not. A 5% rate compounded monthly is really 5.12% APY. Here is how the math works and what