
Why Do Banks Charge Monthly Maintenance Fees on Checking Accounts?
This article is educational, not financial advice. Check your own bank's fee schedule before making any account decisions.
Key takeaways
- Banks charge maintenance fees to cover operating costs (branches, staff, technology, security) and to turn basic accounts into profitable ones.
- Typical fees run about $5.50 per month for basic checking and $15 to $16 for interest-bearing accounts, according to fee surveys.
- Most fees are avoidable through direct deposit, a minimum balance, or simply switching to a no-fee online bank or credit union.
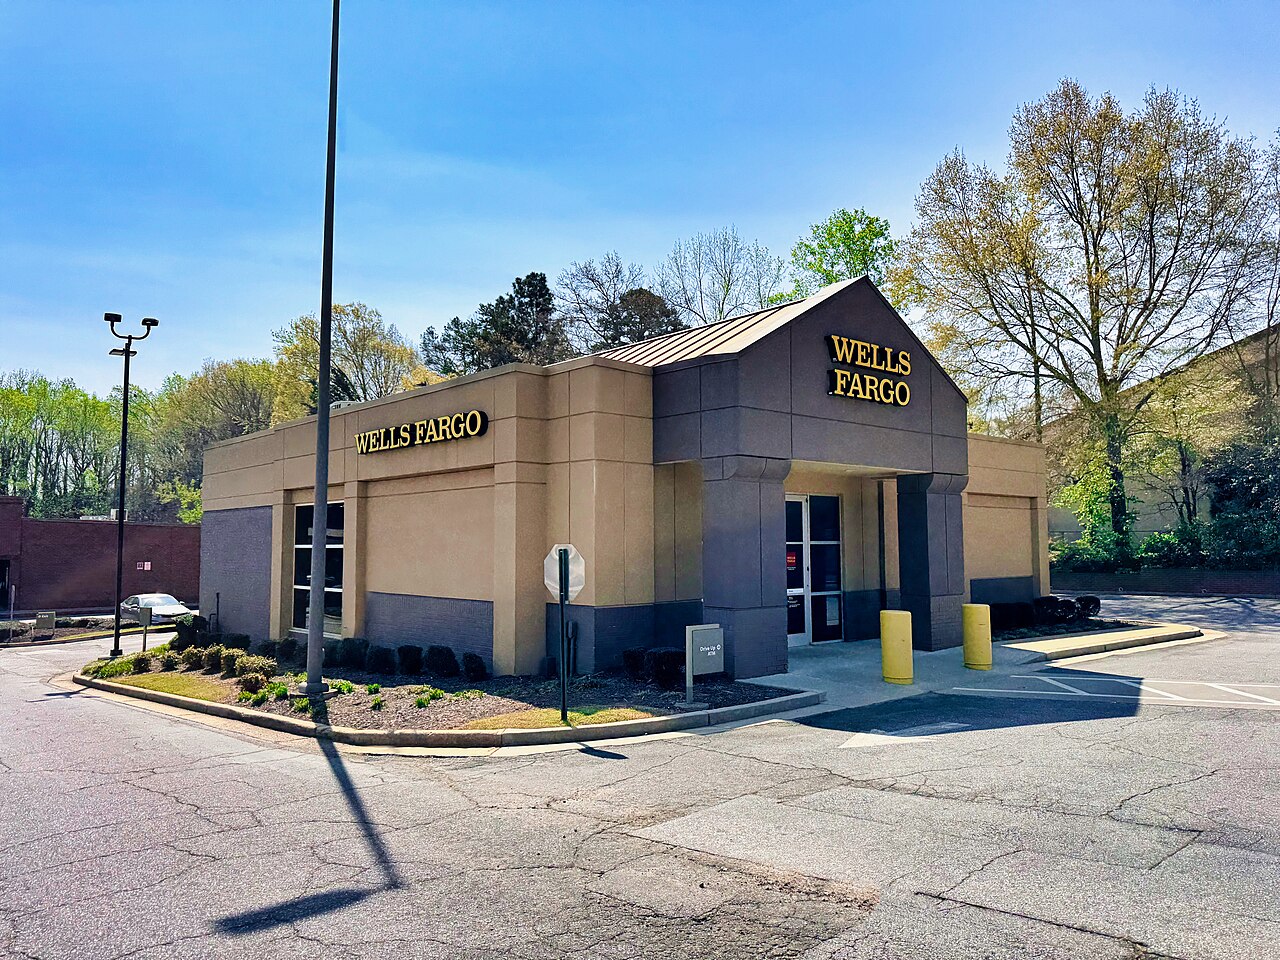
A bank branch. Branches, staff, and technology cost money to run, and maintenance fees help pay for them. Photograph: Harrison Keely
Every month, millions of checking account holders see a small line on their statement: monthly maintenance fee, $5, $10, sometimes more. The account just sits there holding money, so the charge feels like paying rent on your own cash. It is not random.
The fee exists for three business reasons, and understanding them is the fastest way to make the charge disappear.
Banks are not charities. A checking account that costs them money to run but earns them nothing is a bad product, and the maintenance fee is how they price that reality. The good news is that nearly every fee comes with a built-in escape hatch, because banks would rather waive your fee than lose you to a competitor.
This article explains the business logic behind the fee, what the fees typically cost, why some institutions charge nothing at all, and the exact conditions that erase the charge.
The business model: why the fee exists at all
A checking account is expensive to provide. The bank maintains branches and ATMs, staffs customer service, processes payments, runs a digital banking platform, and protects customer data with security technology. As Wells Fargo's fee guide puts it, financial institutions use maintenance fees to pay for operating costs like maintaining bank branches and features such as ATM reimbursement or rewards.
There are three layers to the logic. First, the fee covers costs directly. An account with a low balance generates almost no lending income for the bank, so the fee makes basic accounts viable.
Second, the fee is a nudge. Banks structure waivers around direct deposit and minimum balances, which keeps deposits inside the bank where they can be lent out and invested. Third, the fee is profit.
Experian notes that banks and credit unions charge these fees partly to pay for operating costs and partly to help boost profits.
This is why the fee is most common at for-profit banks with branch networks, and rarer at online banks and credit unions. Online institutions have lower overhead and staffing expenses, so many offer no-fee accounts. Credit unions, which are not-for-profit, tend to charge lower fees or none at all.
What the fees actually cost
The amount depends on the account type. Basic noninterest checking accounts that charge a fee average about $5.50 per month, according to fee surveys cited by LegalClarity. Interest-bearing checking accounts cost significantly more, averaging around $15 to $16 per month.
Premium accounts with perks like rewards programs or higher interest rates can run $25 or more per month.
The bank usually deducts the fee on a fixed date each month or at the end of the statement cycle, so the charge is predictable. A separate but related charge is the dormancy or inactivity fee: if an account sits unused for several months to a year, some banks deduct an additional $5 to $25 per month on top of the standard fee. After a longer stretch of inactivity, generally three to five years depending on the state, the bank must turn the remaining funds over to the state as unclaimed property.
Over a year, even a modest fee compounds. At $12 a month, an account holder pays $144 a year simply for keeping the account open, money that is entirely avoidable with the right setup.
ATMs, branches, and payment processing are part of the operating cost that maintenance fees offset. Photograph: Syced
Why some banks charge nothing
If fees are so useful, why do some institutions skip them? The answer is cost structure and strategy. Online banks without branches spend far less on real estate and tellers, so they can offer free checking and still profit from the deposits.
Credit unions return surplus to members rather than shareholders, which keeps fees low.
Free checking is also a customer-acquisition strategy. A no-fee account gets customers in the door, and the bank then earns money when those customers take loans, open credit cards, or keep large balances. The maintenance fee is, in this sense, a segmentation tool: banks charge the customers who cost the most to serve and generate the least revenue, while competing for everyone else with free accounts.
This is why switching institutions is one of the most reliable ways to kill the fee. The fee is not a law of nature; it is a pricing choice, and competitors have made a different one.
How to avoid the fee: the standard playbook
Almost every maintenance fee can be waived by meeting one of a few standard conditions. These are the ones Experian lists, and they appear in nearly every bank's fee schedule.
Set up direct deposit. Many banks waive the fee when you receive qualifying direct deposits each statement period. Qualifying deposits usually include employer paychecks, government benefits, and pensions deposited electronically. Check the bank's rules for the minimum amount required.
Keep the required minimum balance. Another common waiver is maintaining a minimum daily balance or an average balance across accounts at the same institution. Some banks calculate it per day, others average across several accounts, so read the fine print.
Link accounts. Some banks waive the checking fee if you hold a linked savings account or other product with them, which is another nudge to keep more of your money inside the institution.
Qualify for a special account. Many banks offer low- or no-fee accounts for students, military members, or seniors. If you qualify, switching account types can erase the fee instantly.
Switch to a no-fee institution. If none of the waivers fit, an online bank or credit union with no monthly fee is the cleanest solution. There is no penalty for moving; the market has made free checking widely available.
Fee structures differ widely between institutions, which is why comparing accounts pays off. Photograph: CesarNS1980
Frequently asked questions
Are monthly maintenance fees negotiable?
Sometimes. Banks publish standard waivers, but calling and asking for a fee waiver or a switch to a no-fee account type often works, especially if you have been a customer for a while. They would rather waive the fee than lose the account.
Do savings accounts have maintenance fees too?
They can. Some savings accounts carry monthly fees with similar waiver conditions, though many online banks and credit unions offer fee-free savings as well.
What is the difference between a maintenance fee and an overdraft fee?
A maintenance fee is charged every month simply for keeping the account open, regardless of activity. An overdraft fee is a one-time penalty charged when you spend more than the account holds. They are separate charges with separate rules.
Can a bank raise the maintenance fee without telling me?
Banks must disclose fee changes, typically by updating the account agreement and notifying customers in advance. This is why reading notices from your bank matters more than most people think.
The bottom line
Banks charge monthly maintenance fees because checking accounts cost real money to operate, and the fee makes low-balance accounts profitable while nudging customers toward direct deposit and higher balances. The fees typically run about $5.50 a month for basic checking and up to $16 for interest-bearing accounts. Almost every one is avoidable: set up direct deposit, hold a minimum balance, or move to a no-fee bank or credit union.
Read your fee schedule once, set up the waiver, and the charge disappears for good.
Latest in Personal Finance
- How inflation makes things cost more
- Why you blank out during tests (and how studying fixes it)
- Fixing eSIM issues when traveling abroad
- Why flight paths look curved on maps
Get one practical money explainer in your inbox each week. Subscribe for the weekly finance desk letter.
Image Credits: Wikimedia Commons / Harrison Keely, Syced, CesarNS1980
Related stories

How your APR is divided by 365 to get daily interest
Lenders divide your APR by 365 for a daily rate, then apply it to your average daily balance. This guide walks through every step

What is the difference between APR and effective annual rate?
APR ignores compounding inside the year; the effective annual rate includes it. A 12.99% APR card really costs 13.80% a year. Worked

APY vs interest rate: what compounding does to your money
APY includes compounding; the interest rate does not. A 5% rate compounded monthly is really 5.12% APY. Here is how the math works and what