
How Buy Now, Pay Later Makes Money Without Charging You Interest
Key takeaways
- Stores pay BNPL providers 2-8% of each transaction, which is the main revenue stream and why the classic Pay in 4 plan can be interest-free.
- Late fees add a second stream: the CFPB found about 4.1% of Pay in 4 loans were assessed fees averaging near $10.
- Longer BNPL loans do charge interest: Affirm's APRs run from 0% to 36%, and Affirm and Afterpay's owner dominate interest-bearing BNPL lending.
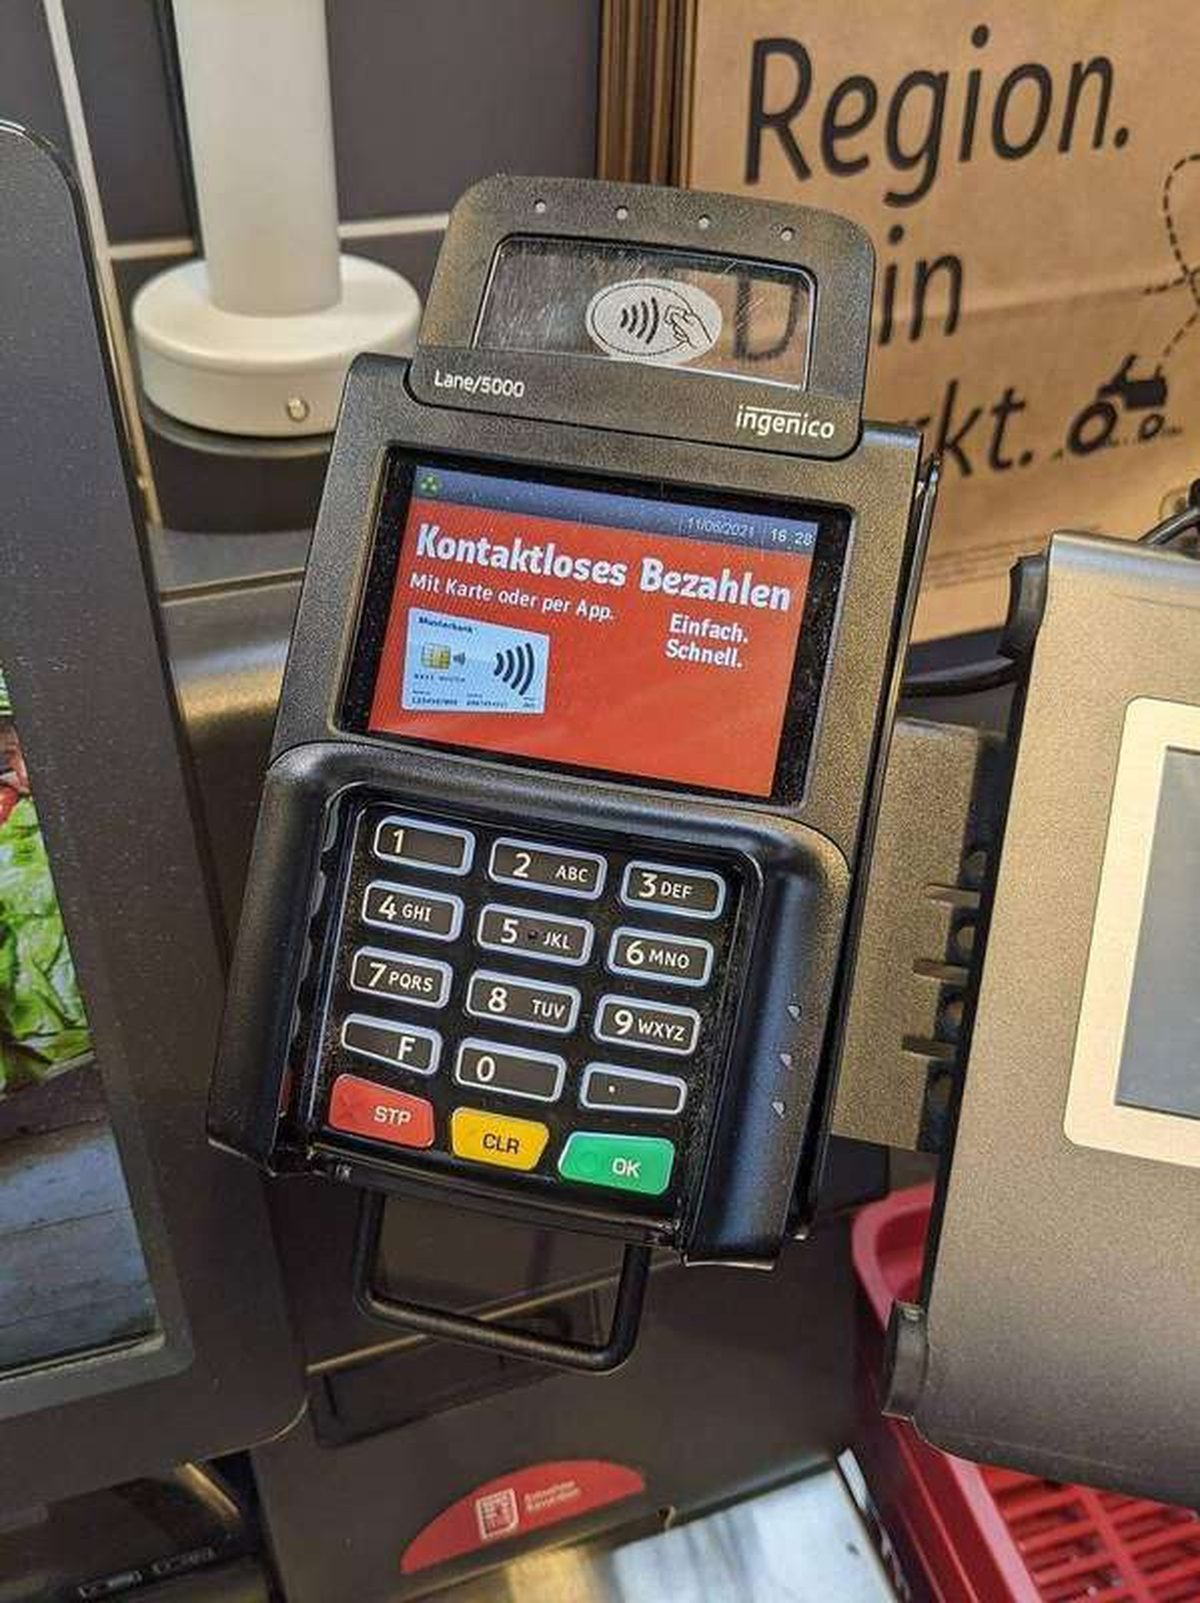
Buy now, pay later lets you split a purchase into installments, usually four payments over six weeks, with no interest if you pay on time. The catch is that "no interest" describes the short plan, not the whole business. BNPL companies make money from three streams: fees charged to merchants, fees charged to late-paying shoppers, and interest on longer-term loans.
This article explains what BNPL actually is, how the merchant-fee money flows, what late fees contribute, where interest quietly enters through longer loans, and why stores agree to pay for all of it.
What BNPL actually is
The flagship product is Pay in 4: you pay 25% of the purchase price at checkout, then three more payments every two weeks. FourWeekMBA's breakdown of Afterpay notes that the company effectively lends 75% of the purchase price to the consumer. Pay on time and there is no interest and no extra cost.
The short plan is genuinely cheap for the shopper. The money has to come from somewhere, and it mostly comes from the merchant, not you.
How the money flows: merchant fees
When you choose BNPL at checkout, the retailer pays the provider a cut of the sale. BNPL platforms charge merchants 2-8% per transaction, compared with roughly 2% for a traditional credit card swipe, according to MyDebtCoach's review of the industry. Sezzle, for example, charges 6.1% plus $0.30 per transaction.
Afterpay's fee is $0.30 plus a variable 4-6% of the transaction value, with the exact rate depending on the merchant's volume, per FourWeekMBA. These merchant fees are the bulk of BNPL revenue: the Congressional Research Service estimated they represent 32-57% of total BNPL revenue in a February 2026 analysis cited by MyDebtCoach.
The provider also takes on the credit risk and pays the merchant upfront for the full purchase amount, so the store gets its money immediately while the BNPL company collects from you over six weeks.
The late-fee revenue stream
BNPL companies insist they do not want you to pay late, and Afterpay says it earns more from merchant commissions than from late fees. But late fees are still a meaningful revenue line. The Consumer Financial Protection Bureau's December 2025 market report put the average assessed late fee near $10 in 2023 data, with 4.1% of Pay in 4 loans assessed late fees, according to MyDebtCoach's summary.
At the company level, Klarna made 17% of its revenue from consumer fees in 2024, and Sezzle made 22%, per the same summary. At the scale these companies operate, a small share of late payers adds up to hundreds of millions of dollars a year.
The fee structures have caps. Afterpay's U. S.
installment agreement sets the late fee at up to $8.00, and the total late fees on one order cannot exceed 25% of the order value, per Feedough's review of the terms. Afterpay also blocks further purchases when a payment is missed, which pushes on-time behavior.
Where interest does enter: longer loans
This is the part the "no interest" marketing obscures. Beyond Pay in 4, BNPL providers offer monthly financing plans for bigger purchases, and those carry real interest. Affirm's own consumer terms state that pay-over-time plans carry 0%-36% APR based on credit, while its Pay in 4 option is 0% APR.
Affirm is the biggest player in this segment. A Federal Reserve analysis published in June 2026 found that Affirm and Block, which owns Afterpay, together represent over 90% of all APR-bearing BNPL originations, per AInvest's coverage.
Affirm lends up to $30,000 on terms stretching to five years. Roughly 63% of all BNPL originations carry 0% APR, which means more than a third do not.
PYMNTS' comparison of provider terms shows the handoff clearly: Affirm's monthly plans run up to 48 months and $20,000 at 0% to 36% APR, Klarna offers monthly financing for 3 to 24 months, and Afterpay's monthly plans reach $20,000 over 3 to 24 months at up to 35.99%. The interest-free product ends where the credit product begins.
One notable exception: Affirm charges no late fees at all, per its company policy. Its revenue comes from merchant fees and interest, not penalties.
Why stores pay to be in the checkout lane
Merchants voluntarily pay double or triple the cost of a card swipe because BNPL lifts sales. Afterpay claims that offering installments increases average order value by as much as 20%, per FourWeekMBA. Stores get higher conversion rates, bigger baskets, and new customers, and they receive the full purchase amount upfront.
That is the whole bargain. You get an interest-free split, the store gets a bigger sale, and the BNPL company takes its cut from the store. Late fees and interest-bearing loans are the second and third acts, and they are where the "free" loan stops being free.
Frequently asked questions
Is buy now, pay later really interest-free?
The classic Pay in 4 plan is interest-free if you pay on time. Longer monthly plans from Affirm, Klarna, and Afterpay can carry APRs up to 36%, 35.99%, and similar rates.
How much do merchants pay BNPL providers?
Typically 2-8% per transaction plus a small fixed fee, versus roughly 2% for a standard credit card. Afterpay charges $0.30 plus 4-6%; Sezzle charges 6.1% plus $0.30.
What happens if I miss a BNPL payment?
You can be charged a late fee, around $8 to $10 per missed payment depending on the provider, with caps tied to the order value. Afterpay blocks new purchases until you catch up.
Does BNPL report to credit bureaus?
Practices vary by provider and plan, and reporting rules have been changing. Check the current terms with the provider before you borrow.
The bottom line
BNPL makes money three ways: merchants pay 2-8% of each sale, late payers contribute fees averaging near $10, and longer-term loans carry interest up to 36% APR. The interest-free Pay in 4 plan is funded by the store's cut, which is why it can exist at all.
Before using BNPL, read the plan's actual terms, because the short plan and the long loan are very different products.
This article is an explainer, not financial advice; for decisions about your own borrowing, consider speaking with a qualified financial professional.
Tags: buy now pay later, BNPL, Klarna, Afterpay, Affirm, finance explainer
Rive News is a research desk producing verified explainers on science, money, and technology.
Related stories
- Why Credit Card Rewards Cost You Money If You Carry a Balance
- Can You Use an eSIM and a Physical SIM at the Same Time?
- Why Hot Water Can Freeze Faster Than Cold: The Mpemba Effect Explained
Subscribe to the Rive News newsletter for one clear, verified explainer every week.
Rive News follows a verification-first standard: every statistic above traces to a cited public source.
Related stories

How your APR is divided by 365 to get daily interest
Lenders divide your APR by 365 for a daily rate, then apply it to your average daily balance. This guide walks through every step

What is the difference between APR and effective annual rate?
APR ignores compounding inside the year; the effective annual rate includes it. A 12.99% APR card really costs 13.80% a year. Worked

APY vs interest rate: what compounding does to your money
APY includes compounding; the interest rate does not. A 5% rate compounded monthly is really 5.12% APY. Here is how the math works and what