
What is an index fund and why beginners hear about it
Key takeaways
- An index fund copies a market index, such as the S&P 500, instead of paying a manager to pick stocks.
- Low fees are the main advantage, and a small fee gap can grow into a six-figure difference over decades.
- Index funds still fall when the market falls, so they suit long-term money, not cash needed soon.
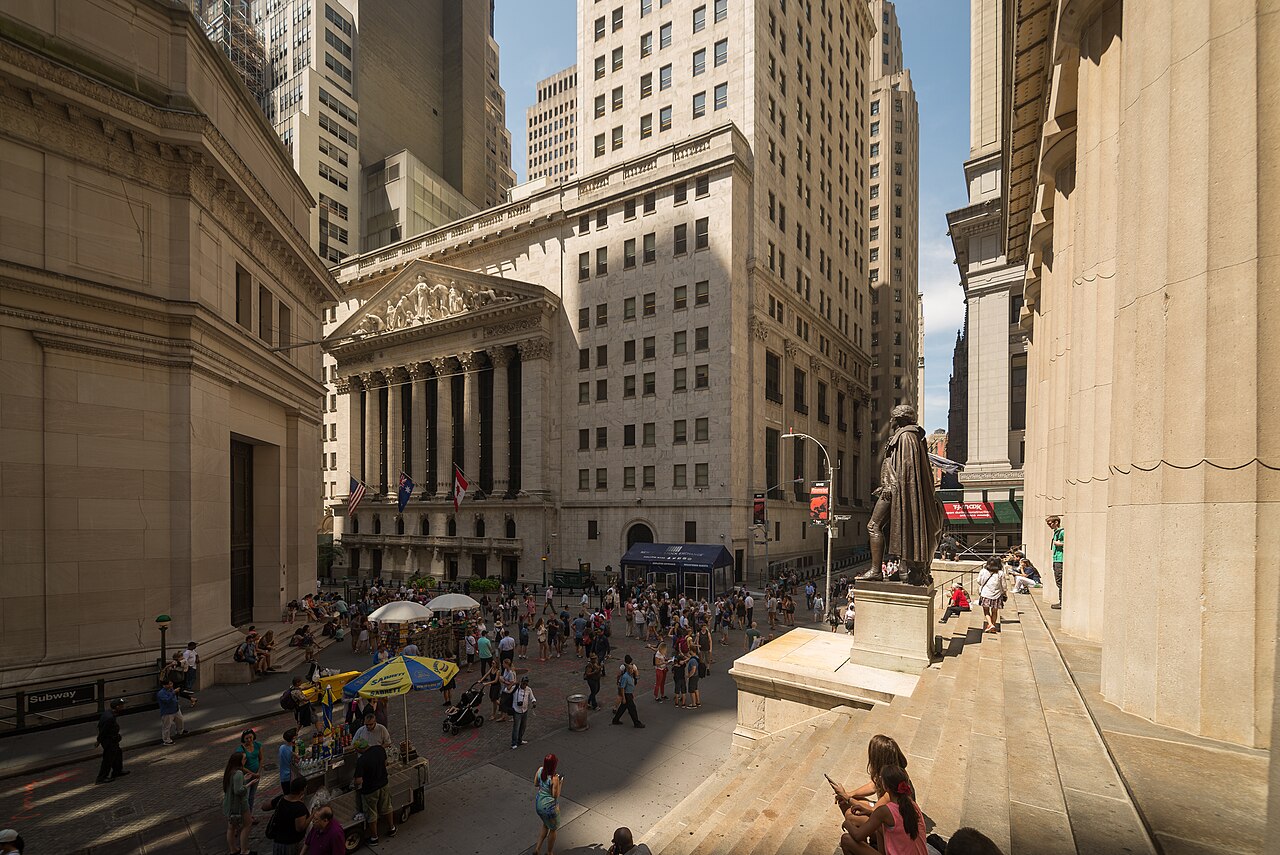
An index fund is a basket of investments that copies a market index. Buy one share of an S&P 500 index fund, and you own a tiny slice of all 500 companies in that index. The fund does not try to beat the market.
It tries to match it, holding the same stocks in the same proportions as the index itself.
Beginners hear about index funds so much because they solve the hardest parts of starting out: which stocks to pick, how to diversify, and how to keep fees low. This article explains what is an index fund and why do beginners hear about it so much, including how it works, what it costs, where it falls short, and what to sort out before buying one. This article is for general information, not financial advice.
What an index fund is
An index is a list that tracks a slice of the market. The S&P 500 tracks 500 large American companies. The Dow Jones Industrial Average tracks 30 blue-chip companies.
A total market index tracks thousands of companies of all sizes. Each index has published rules for which companies belong and how much weight each one carries.
An index fund follows those rules. Investopedia describes an index fund as an investment vehicle, usually a mutual fund or an exchange-traded fund (ETF), that tracks a specific market index and uses a passive strategy to mirror the holdings and performance of that index. The fund buys the stocks in the index and holds them, trading only when the index itself changes.
No manager sits in a room picking winners.
The idea is not new. Index investing emerged in the 1970s, when John Bogle, founder of Vanguard, introduced the first index mutual fund for individual investors. At its launch in 1976, the Vanguard 500 Index Fund was met with skepticism and dubbed Bogle's Folly, according to Investopedia.
From about 10 million dollars at the start, United States index funds grew to more than 16 trillion dollars by year-end 2024. The joke did not age well.
How an index fund works
When you buy a share of an index fund, your money is spread across the index. An S&P 500 fund buys shares in all 500 companies, weighted by size, so the biggest companies take up the biggest share of the fund. When a company enters or leaves the index, the fund adjusts to match.
When the index rises or falls, the fund rises or falls with it.
The fund can come in two wrappers. A mutual fund prices once a day and is bought directly from the fund company or through a broker. An ETF trades on an exchange through the day like a stock.
Both wrappers can hold an index, and both can be cheap or costly. The wrapper does not tell you the fee. The expense ratio does.
The expense ratio is the yearly cost of owning the fund, expressed as a percentage of your investment. Clark. com reports that expense ratios of 0.03 percent to 0.10 percent are common for index funds, while actively managed funds typically charge 0.50 percent to 1.00 percent or more, with some adding sales loads on top.
A 0.04 percent expense ratio means you pay 4 dollars a year for every 10,000 dollars invested. A 1 percent fee means 100 dollars a year on the same sum.
Why beginners hear about it so much
Beginners hear about index funds because they remove the two hardest decisions in investing: what to buy, and when to sell. A new investor who picks individual stocks must research companies, judge prices, and decide when to get out. An index fund buyer makes one decision, which market to own, and then holds it.
That simplicity is why the fund shows up in nearly every beginner guide.
Diversification is the second reason. One share of a broad index fund spreads money across hundreds or thousands of companies. A single company can stumble without sinking the fund, since no one holding matters that much on its own.
Compare that with buying a single stock, where one bad earnings report can cut the whole position. Diversification does not remove risk, but it changes the risk from one company's fate to the whole market's fate.
Low fees are the third reason, and the one that compounds. Clark. com worked through the math on a 100,000 dollar portfolio growing at 10 percent a year for 30 years.
With an index fund charging 0.04 percent, the ending balance came to about 1.72 million dollars. With an actively managed fund charging 0.63 percent, the balance came to about 1.52 million dollars. The fee gap alone cost roughly 200,000 dollars.
Fees look small in a single year and enormous across a career.
The fourth reason is the track record of the alternative. Clark. com, citing the SPIVA Scorecard, reports that over a recent 15-year period, roughly 90 percent of actively managed large-cap United States stock funds underperformed the S&P 500. Most professionals paid to beat the market did not beat it, after fees.
A beginner who buys the index skips that contest entirely and keeps the market's return minus a tiny fee.
What index funds cost in practice
Expense ratios vary, so check the number on any fund you consider. Clark. com lists real funds from a Vanguard 401(k) plan: the Vanguard 500 Index fund (VFIAX) at 0.04 percent, or 40 dollars a year on a 100,000 dollar investment, and the Vanguard Total Stock Market Index fund (VTSAX) at the same 0.04 percent.
By contrast, the popular actively managed Fidelity Contrafund (FCNTX) charged 0.63 percent, or 630 dollars a year on the same sum.
The risks beginners miss
Index funds are often described as safe, which overstates the case. They are diversified, not protected. When the market falls, an index fund falls with it.
The manager cannot move to cash, dodge a weak sector, or hedge during a downturn, because the fund must hold the index. Investopedia lists no downside protection and limited flexibility among the cons of index funds.
Concentration is a subtler risk. The S&P 500 is weighted by company size, so the biggest companies dominate it. Investopedia notes that in 2025, the seven large tech companies known as the Magnificent Seven, Apple, Amazon, Alphabet, Meta, Microsoft, NVIDIA, and Tesla, made up almost a third of the index.
An S&P 500 fund is diversified across 500 names, but nearly a third of its value rides on seven companies. A total market or global fund spreads that weight a little wider.
Time horizon is the risk that matters most for beginners. Money needed within a year or two does not belong in a stock index fund, because the market can fall and stay down for months. Money meant for a house deposit next year, a tuition bill, or an emergency fund belongs in cash or a short-term savings vehicle.
Index funds suit money that can stay invested for years, through ups and downs, without being needed on a deadline. The difference between saving and investing sets that boundary clearly.
Types of index funds
Not all index funds track the same market. The main types cover different slices, and many investors hold more than one.
- Broad market funds track a whole market, such as the total United States stock market or the global stock market. Examples include the iShares Russell 3000 ETF and the Vanguard Total World Stock ETF. These are often the core holding in a simple portfolio.
- Large-cap funds track big companies, usually through the S&P 500. Examples include the SPDR S&P 500 ETF and the Fidelity 500 Index Fund. They suit investors who want exposure to America's biggest corporations.
- International funds track markets outside the United States, covering developed and emerging markets. Examples include the iShares Core MSCI EAFE ETF and the Vanguard FTSE Emerging Markets ETF. They add geographic diversification.
- Sector funds track one industry, such as technology, health care, or real estate. They concentrate risk in a single sector and suit investors who already hold a broad core fund.
- Bond index funds track bond markets, such as the Bloomberg United States Aggregate Bond Index. Examples include the iShares Core United States Aggregate Bond ETF and the Vanguard Total Bond Market ETF. They are steadier than stock funds but grow more slowly.
What to sort out before buying
Index funds work best after the basics are in place. First, build an emergency fund of three to six months of expenses in cash, since investing the emergency fund turns a job loss into a forced sale. Second, pay off high-interest debt, since a credit card charging 20 percent costs more than any realistic investment return.
A guide to how credit card grace periods save money covers one part of that debt picture.
Can index funds lose money?
Yes. An index fund falls when its index falls, and there is no manager to cushion the drop. Over long periods, broad markets have recovered from falls, but no fund guarantees that, and short-term money should not sit in a stock fund.
How much money do I need to start?
Many ETFs have no minimum beyond the price of one share, and many brokers offer fractional shares. Some mutual funds set minimums, often 1,000 to 3,000 dollars. Check the fund's minimum before you open the account.
Are index funds better than picking stocks?
For most beginners, yes, because of low fees, instant diversification, and the record of active funds trailing the index. Picking stocks can beat the market, but it takes research, time, and discipline, and most professionals who try it fail to beat the index over long periods.
What is the difference between an index fund and an ETF?
An index fund is a strategy: copy an index. An ETF is a wrapper: a fund that trades on an exchange. An index fund can come as a mutual fund or as an ETF, and an ETF can be active or passive.
Check the expense ratio, not the label.
The bottom line
An index fund copies a market index, charges a tiny fee for doing so, and spreads your money across hundreds of companies in one purchase. That mix of simplicity, diversification, and low cost is why beginners hear about it so much. Sort out the emergency fund and high-interest debt first, then pick a broad, low-cost fund, buy on a schedule, and hold it for years.
The strategy is boring by design, and that is the point.
Tags: index funds, investing, beginner investing, personal finance
Latest in Finance
- How a credit card grace period saves money
- Buy now, pay later and your money
- The difference between saving and investing
- How to buy a stock
Subscribe for one practical money explainer each week.
Related stories

How your APR is divided by 365 to get daily interest
Lenders divide your APR by 365 for a daily rate, then apply it to your average daily balance. This guide walks through every step

What is the difference between APR and effective annual rate?
APR ignores compounding inside the year; the effective annual rate includes it. A 12.99% APR card really costs 13.80% a year. Worked

APY vs interest rate: what compounding does to your money
APY includes compounding; the interest rate does not. A 5% rate compounded monthly is really 5.12% APY. Here is how the math works and what